← All sectors
Sector 09 · Data Centres
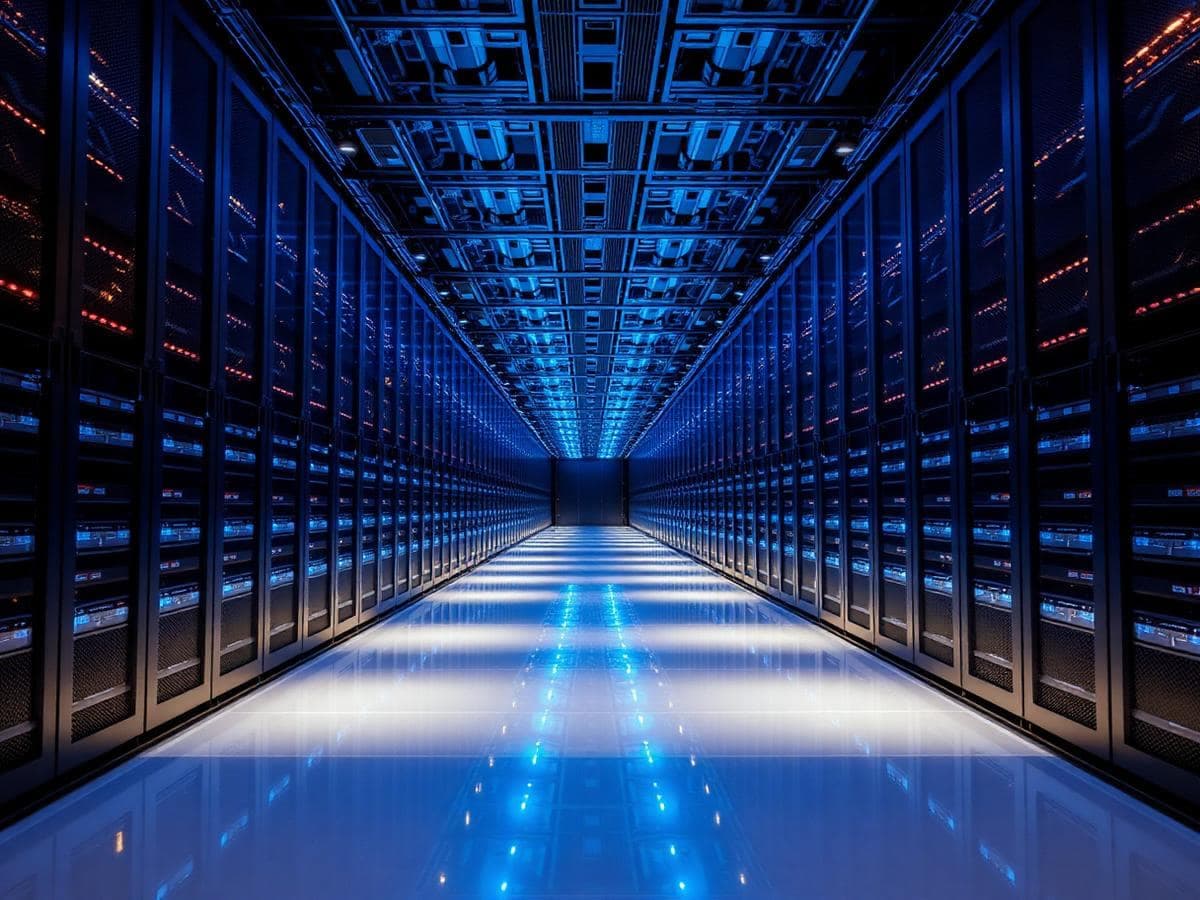
Hyperscale, colocation and edge.
The physical infrastructure of the cloud economy — from 200 MW hyperscale campuses to edge nodes.
Take-up (MW)
240 MW
+120% YoY
Vacancy
2%
record low
Prime yield
8.5%
-40 bps YoY
AI-ready pipeline
1.4 GW
+200% YoY
Overview
Power is the product.
Data-centre demand is now dictated by grid capacity, water availability and land assembly at the transmission edge. AI training loads are pushing rack densities from 8kW to 50kW+, forcing liquid cooling and rewriting the design brief. We advise hyperscalers, colocation operators, developers and institutional capital across origination, delivery and exit.
Themes we're tracking
The forces reshaping the sector.
01
AI compute
GPU clusters driving rack density, liquid cooling and 100+ MW campus formats.
02
Grid queues
Transmission connection wait 24–48 months in every core market.
03
Land-and-power
Land assembly with pre-agreed connection now the primary value driver.
04
Sovereign compute
Government-anchored sovereign-cloud tenders creating institutional demand.
05
Water use
Cooling-water consumption a rising planning and social-licence constraint.
06
Edge
Distributed micro-DC footprint expanding into tier-2 and tier-3 cities.
How we help
Mandates we deliver.
01
Land-and-power sourcing
Off-market origination of sites with pre-agreed grid and water connection.
02
Occupier and hyperscaler
Site selection, RFP support and lease negotiation for cloud and colocation tenants.
03
Development advisory
Feasibility, MEP specification, phasing and delivery oversight.
04
Capital markets
Forward funding, platform acquisitions and stabilised-asset disposals.
05
Valuation
Specialist valuation for lending, IFRS and portfolio review.
Ready to view
See the assets, on site.
Related sectors